



Reference prices this week
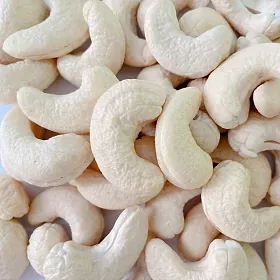
- Kernel W320 FOB: indicative range USD 6,800–6,858/ton
- Kernel W240 FOB: typically 15–20% above W320
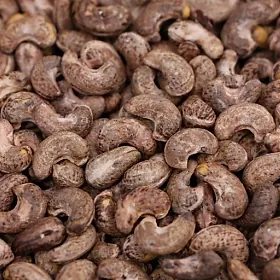
- Raw cashew imports: above VND 40,000/kg
- CNF HCMC for West African raw: reference VINACAS daily postings
Key destination markets Q1/2026
- USA: 32,800 tons · USD 221.17 million · 88.68% share within US-bound shipments · up 13.6%
- Germany: +26% — fastest-growing Q1 market
- Canada: +52% — standout growth
- China: -16% by volume; spot buying pressured prices
- Netherlands: USD 82 million (-3%)
Crop + macro context
- Vietnam 2026 crop: peak harvest in April-May
- Raw material: Q1 trade deficit ~USD 370 million; processing value-add of 4.1× (export/import ratio)
- Middle East conflict: regional orders "nearly frozen"
- Ocean freight: stable vs Q4/2025
This week's insight
Germany and Canada are the strongest Q1 non-traditional markets — a clear opening for exporters to diversify if Middle East remains soft. Separately, the US accounting for 88.68% of US-bound shipments flags concentration risk: over-reliance on one market becomes costly if FSMA enforcement tightens or tariff policy shifts.
Exporters with US contracts should audit compliance clauses now — food safety standards for Salmonella, Listeria, and heavy metals are tightening across US and EU buyers.